A Wallet Market Already Primed for Invisible Blockchain
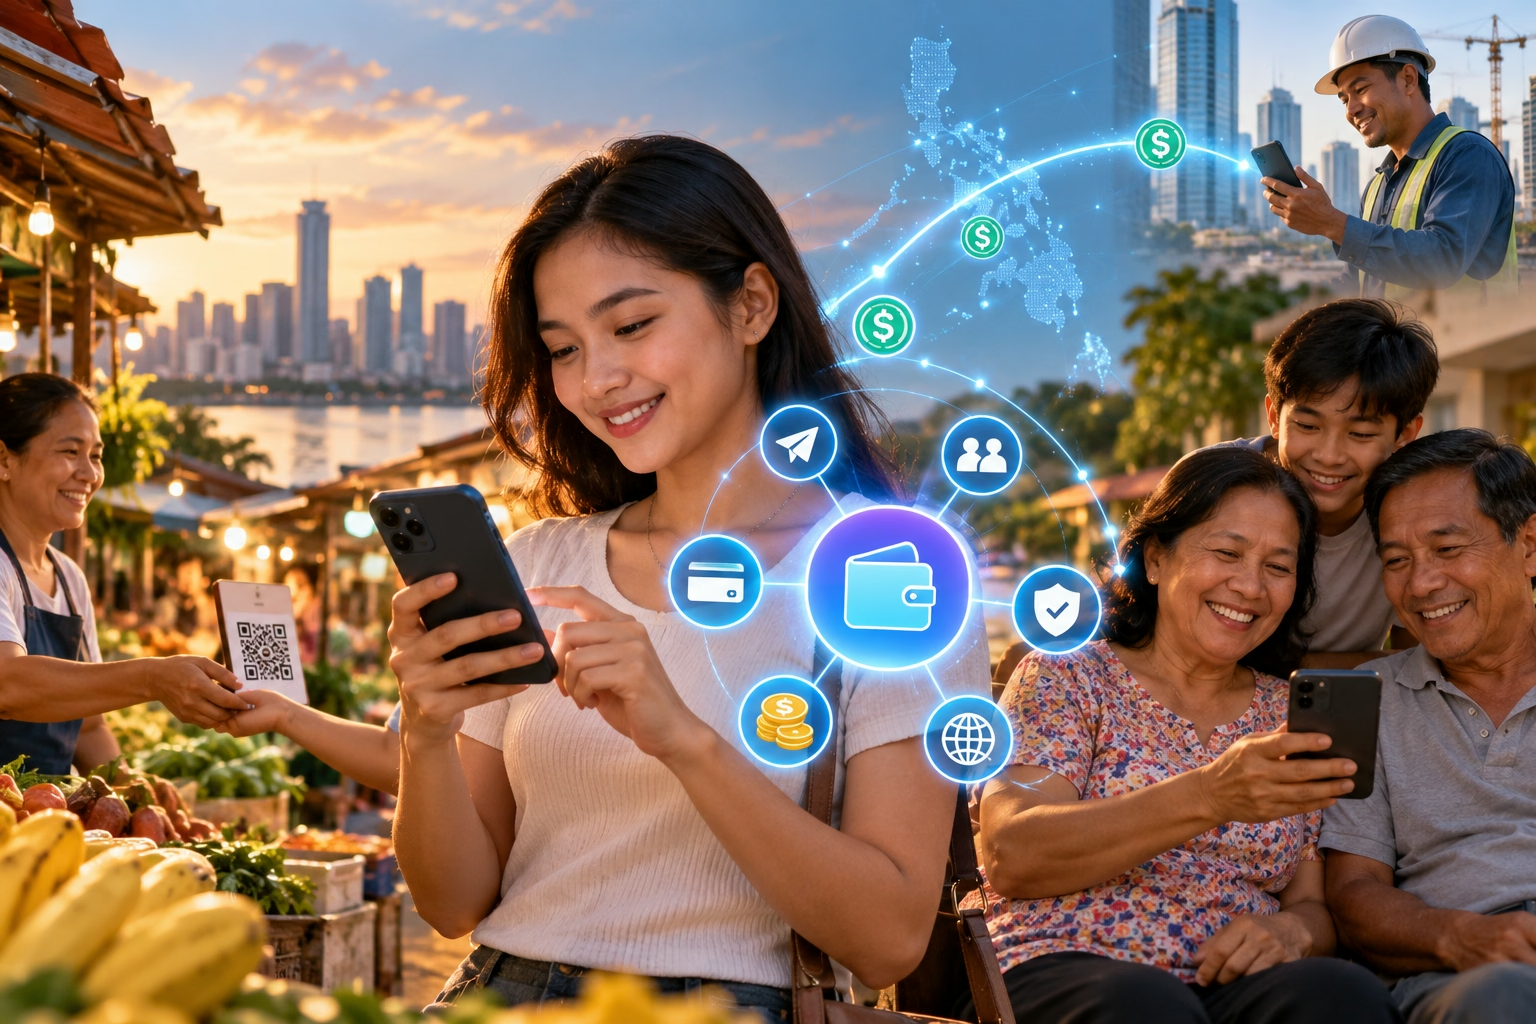
The Philippines did not arrive at Web3 through crypto speculation. It arrived through habit. Mobile wallets such as GCash and Maya grew from roughly 20 million users before the pandemic to more than 94 million, and by 2025 mobile wallet penetration had surpassed traditional bank account ownership. For millions of Filipinos, the smartphone is already the primary financial interface—used for payments, remittances, bills, and savings.
That baseline changes the adoption question. The challenge is no longer persuading people to use a digital wallet. It is making a Web3 wallet behave like the fintech apps they already trust. Account abstraction is the technical answer to that expectation.
What Account Abstraction Actually Removes
Traditional Web3 wallets were built for a crypto-native minority. A new user had to write down a 12- to 24-word seed phrase, acquire a volatile gas token before making any transaction, and understand which chain they were operating on. Onboarding completion rates for that flow have historically hovered around 23%. For a remittance-dependent market where speed and cost determine usefulness, those friction points are disqualifying.
Account abstraction, standardized through ERC-4337, replaces the externally owned account model with a smart contract wallet. The user no longer manages a private key directly. Instead, the wallet can enforce social recovery, batch transactions, and—critically—allow a third party to sponsor network fees through a paymaster. The blockchain still settles the transaction, but the user experience recedes into the background.
In practice, this means signing up with a Google account or a biometric passkey, topping up with a local payment method, and sending stablecoins without ever holding ETH or TRX for gas.
Real Deployments Already Running in the Philippines
Account abstraction is not a 2026 thought experiment in the country. Singapore-based Account Labs launched its UniPass Wallet in the Philippines with account abstraction at the core: users create a self-custody wallet using a Google login and top up through any Mastercard or Visa card, including GCash. The product was tested in the Philippines before expanding elsewhere in Southeast Asia, precisely because the market already understood wallet-based finance.
The infrastructure layer is moving as well. In August 2026, Coins.ph—which counts 18 million confirmed users in the Philippines—integrated the Tempo payments blockchain, enabling native gas abstraction for USDT and USDC transfers. Users can now pay network fees directly in the stablecoin they are sending, with settlement in roughly half a second. The integration explicitly targets remittance senders and everyday wallet users, not DeFi traders.
The Regulatory Layer Is Catching Up—Carefully
The Bangko Sentral ng Pilipinas has not treated wallet innovation as a regulatory afterthought. The central bank has been building an interoperable payment framework linking banks and e-wallets, and it has maintained activity-based supervision over virtual asset service providers. A June 2026 memorandum tightened asset listing standards and banned anonymity-enhancing cryptocurrencies, signaling that consumer protection—not open experimentation—is the governing principle.
For account abstraction providers, that cuts both ways. Compliance-heavy design is non-negotiable, but the regulatory direction favors wallets that behave like regulated financial tools rather than anonymous crypto interfaces. The BSP framework effectively rewards the “fintech-like” UX that account abstraction enables.
Why the Philippines Is the Test Case, Not the Exception
The numbers explain the urgency. Coins.ph has 18 million confirmed users; MiniPay recorded 14 million registered users and 4.23 million weekly active USDT users by March 2026. Crypto usage in the Philippines rose from 17.8% to 22.5% in a single year, driven largely by remittances and small-value transfers. When a market already moves money through wallets daily, the winning Web3 product will not ask users to learn a new financial language. It will hide the blockchain and deliver the transaction.